A value add strategy means buying a property below its potential, actively raising net operating income through renovation, leasing, or management fixes, then selling or refinancing at a higher valuation. It sits in the middle of the risk-return spectrum, above core and core-plus, below ground-up development. The moment you commit to this approach, two things follow: you need a discounted cash flow model that captures the property’s future stabilized state, and you need financing structured for short-term rehab rather than a standard permanent loan.
TL;DR:
- Value-add financing typically involves interest-only bridge loans with short-term funding, requiring detailed budgets and staged draws for renovation and lease-up phases.
- Accurate DCF modeling must include renovation schedules, lease absorption timelines, vacancy during transition, and realistic rent escalations to reflect the property’s evolving cash flow.
- Most deals need at least 15% cash equity from sponsors, with budgets split into hard costs, soft costs, and contingencies, and require both as-is and as-stabilized appraisals per Freddie Mac standards.
- Execution risks such as contractor selection, lease-up pace, and refinancing assumptions are the main failure points, necessitating conservative underwriting and contingency planning.
- Special considerations apply to medical office and industrial assets, requiring tailored tenant retention strategies, and benefiting from expert valuation and lease review support.
Table of Contents
- What is value-add real estate investing and who does it fit?
- Common value-creation strategies and initiatives
- Underwriting and valuation: DCF, as-is versus as-stabilized
- Financing value-add deals: loan products, lender tests, and sizing
- Risks, common failure modes, and mitigation strategies
- A practical checklist for evaluating a value-add deal
- Applying value-add tactics to medical office and industrial assets
- How Ardor CRE helps you underwrite and execute value-add deals
- Sources
- FAQ
What is value-add real estate investing and who does it fit?
Value-add real estate describes assets bought with the intent to increase income through direct intervention rather than passive holding. That covers a wide range: multifamily buildings with dated units, office towers with high vacancy, medical office buildings with below-market rents, industrial warehouses needing functional upgrades, and small commercial retail centers with weak tenant mix.
Core assets are stabilized, fully leased, and priced for lower, steady returns. Core-plus adds a modest management lift. Opportunistic investing involves ground-up construction or near-total repositioning with the highest risk. Value-add sits between core-plus and opportunistic: enough disruption to require active management, not so much that the asset carries development-level risk.
This strategy fits sponsors with construction or leasing experience, adequate liquidity to absorb budget overruns, and access to deal flow that isn’t already competed over by institutional buyers. It also fits investors with a medium risk tolerance who want returns above what a fully leased trophy building offers, without taking on entitlement or construction-from-scratch risk.
Adaptive reuse is a more aggressive variant, converting a building’s use entirely, such as an office tower into residential or a warehouse into flex space. Recent ULI research on adaptive reuse found that these conversions can produce strong returns while also improving long-term market value, provided architects, engineers, and preservation specialists coordinate early on entitlement and design risk.
Common value-creation strategies and initiatives
The mechanics of value creation vary by asset type, but they cluster around a handful of proven levers.
- Renovation and unit upgrades: interior and common area improvements that support a rent premium, budgeted with hard costs, soft costs, and a contingency.
- Lease-up and re-tenanting: filling vacancy through targeted marketing, tenant improvement allowances, and short-term concessions to establish momentum.
- Operational improvements: replacing property management, renegotiating service contracts, and auditing CAM charges to cut unnecessary expense leakage.
- Tenant retention: offering renewal terms structured around net present value rather than face rent, particularly effective for medical and office tenants whose relocation costs are high.
- Repositioning and adaptive reuse: rebranding an asset or converting its use, often supported by historic tax credits or green infrastructure funding that improve project feasibility.
Medical office value-adds carry their own wrinkles: specialized build-out costs, longer credentialing timelines when a tenant moves suites, and lease negotiation cycles that run longer than standard office deals. Industrial value-adds tend to center on clear height, dock door counts, and power capacity rather than cosmetic upgrades.
Pro Tip: Before committing to a renovation budget, get contractor bids on the three most expensive line items first. That’s usually where estimates drift the most.
Underwriting and valuation: DCF, as-is versus as-stabilized
Value-add deals rarely behave like a flat income stream, so a direct capitalization approach misses the point. RICS guidance on valuation competency notes that discounted cash flow modeling has become the standard for assets where future cash flows will change materially, and that sensitivity and scenario analysis are increasingly expected practice rather than optional extras.
A workable DCF for a value-add deal needs to model the transition period explicitly, not just the eventual stabilized number. Key inputs include:
- Renovation budget and phasing, tied to a realistic draw schedule.
- Lease-up timeline, including absorption pace by unit or suite.
- Rent escalation assumptions, benchmarked against comparable renovated properties.
- Vacancy loss during the transition period, not just at stabilization.
- Capital expenditure reserves and an exit cap rate consistent with the asset’s stabilized risk profile.
Appraisers and lenders typically require both an as-is value, reflecting the property in its current condition, and an as-stabilized value, reflecting the property after renovation and lease-up. Freddie Mac’s underwriting standard requires both as-is and as-stabilized appraisals for its value-add loan products, a discipline that forces sponsors to document realistic rent premiums rather than assume them.
Sensitivity tables built around rent growth, renovation cost, and lease-up speed give lenders and investors a clear view of downside exposure. Presenting a base case alongside a slower lease-up and a higher-cost scenario is more persuasive than a single-point projection, and it mirrors what institutional underwriters expect to see.
Financing value-add deals: loan products, lender tests, and sizing
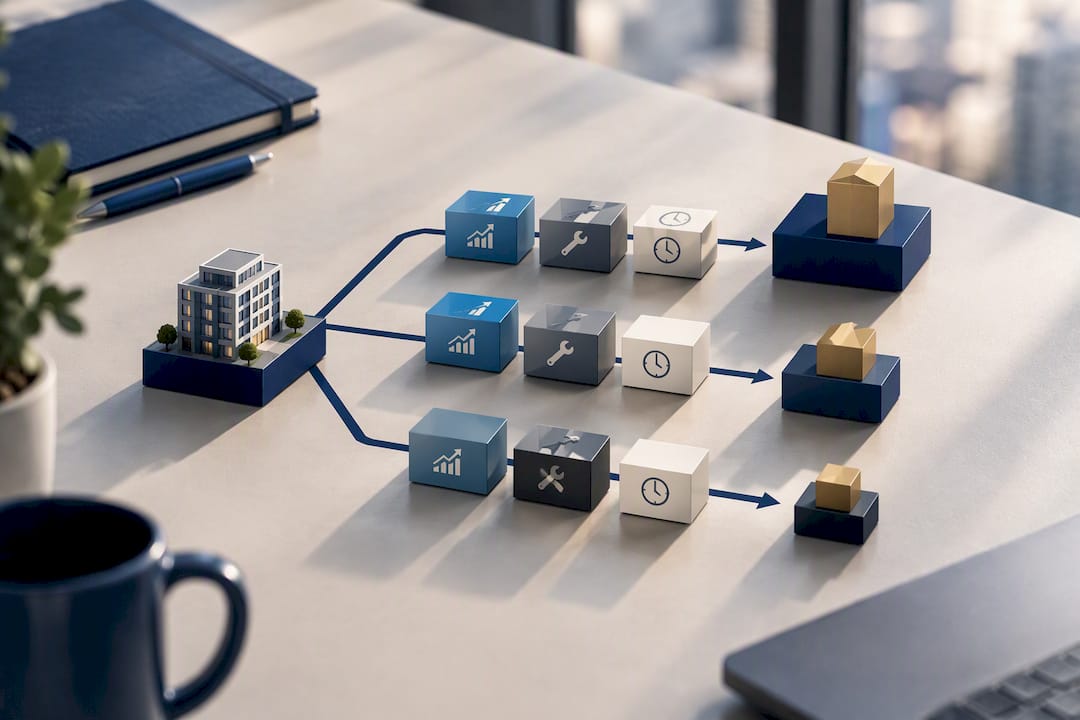
Most value-add deals use bridge or short-term financing rather than a conventional permanent loan, because the property’s income doesn’t yet support long-term debt sizing. These loans are typically interest-only, funded partly through draws tied to renovation milestones, with an expectation of refinancing once the property stabilizes.
Freddie Mac’s Optigo® Value-Add Loan and its Moderate Rehab Loan are two structured products built for this transition period. Renovation budgets for Optigo® Value-Add loans typically run $10,000 to $25,000 per unit, while Moderate Rehab budgets extend to $25,000 to $60,000 per unit. Both require as-is and as-stabilized appraisals, set loan-to-value and debt coverage ratio thresholds, and impose completion guaranty or escrow requirements to protect against unfinished work.
- Sponsors are commonly expected to bring roughly 15% cash equity into the deal, sometimes alongside higher liquidity or net worth requirements than a stabilized acquisition would demand.
- Rehab budgets are frequently split into hard costs, soft costs, and a contingency in the range of 10% to 15%, which lenders expect to see documented rather than estimated loosely.
- Draw mechanics reimburse sponsors as work completes, which means cash flow planning has to account for the lag between paying contractors and receiving reimbursement.
Financing terms shape the deal itself. A tighter rehab budget or a shorter interest-only period compresses how much renovation scope is realistic, and it forces a more conservative exit cap-rate assumption if lease-up runs behind schedule.
Risks, common failure modes, and mitigation strategies
Value-add returns depend on execution, and execution is where most deals underperform their pro forma.
- Execution risk: vet contractors before closing, structure payments around phased draws, and size contingency budgets to the property’s age and scope rather than a flat percentage.
- Leasing risk: underwrite lease-up velocity conservatively, choose a broker with track record in the specific submarket, and stay flexible on tenant improvement and lease term structure to close deals faster.
- Financing and refinance risk: stress test debt coverage ratio under a slower lease-up scenario, maintain an equity cushion, and pre-underwrite the refinance exit before committing to the bridge loan.
- Regulatory and entitlement risk: confirm zoning and permitting requirements early, and budget contingency for fee increases or permit delays that push the renovation timeline.
Pro Tip: Run your refinance scenario at a debt coverage ratio one full turn below your base case. If the deal still works, you have real margin.
A practical checklist for evaluating a value-add deal
Before committing capital, work through this sequence.
- Validate the market: check absorption trends, rent comps from renovated comparable properties, and submarket demand drivers.
- Validate the scope: build a detailed rehab budget with contractor estimates and a documented contingency plan.
- Validate the model: run a DCF with both as-is and as-stabilized assumptions, then stress test rents, costs, and timeline.
- Confirm the financing plan: size the loan, quantify equity needs, and understand lender conditions and fallback options if terms shift.
- Check the sponsor and reporting structure: track record on comparable projects, reporting cadence, and governance around draws and budget changes.
Two areas deserve extra scrutiny before signing anything:
- Whether the lease-up strategy accounts for realistic marketing lead time, not just optimistic absorption.
- Whether the loan sizing matches actual debt coverage ratio expectations rather than a rough estimate.
Applying value-add tactics to medical office and industrial assets
Medical office tenants rarely relocate over a modest rent increase, since credentialing and build-out costs run high. NPV-based retention offers often beat a full vacancy and re-lease cycle. On the sell versus refinance question, run both a CMBS refinance and a sale against current debt coverage ratio and rate assumptions before deciding. Multi-tenant buildings give medical practices and industrial users more flexibility to absorb vacancy without a single tenant’s departure sinking the asset. Commercial real estate advisors support these decisions through valuation, lease review, and tenant improvement planning.
— Jim
How Ardor CRE helps you underwrite and execute value-add deals
Running the numbers on a value-add deal is one thing. Getting the as-is and as-stabilized valuation right, structuring lease terms that protect your rent roll, and modeling the DCF with realistic assumptions is another. Ardor CRE’s commercial real estate services cover valuation, DCF modeling, lease review, and landlord representation for medical, office, and industrial owners. Request a valuation review or a lease abstract before you finalize your underwriting.
Sources
- RICS guidance — valuation competency and DCF emphasis
- ULI — Old Is New: The business case for adaptive reuse (2025)
- Freddie Mac — Optigo® Value-Add Loans (product documentation)
FAQ
What is value-add in real estate?
Value-add in real estate means buying a property below its income potential and actively raising net operating income through renovation, leasing, or operational improvements. It sits between core-plus and opportunistic investing on the risk-return spectrum, offering higher returns than a stabilized asset in exchange for execution risk during the transition period.
What is the 3-3-3 rule in real estate?
Definitions of the 3-3-3 rule vary across sources and it isn’t a standardized industry benchmark. A common version applies it to value-add timing: roughly three months to stabilize operations, three years to execute the business plan, and a three-year hold before exit, though sponsors adjust this based on asset type and market conditions.
What is the 7% rule in real estate?
Some investors use it loosely as a target cap rate or cash-on-cash return threshold, but underwriting a specific deal should rely on comparable rent and sales data rather than a fixed rule of thumb.
How much money do I need to invest to make $10,000 a month?
The capital required depends entirely on the property’s cap rate, leverage, and net operating income after debt service, so there’s no fixed dollar figure that applies across deals. A sponsor evaluating this should model actual comparable properties and financing terms, such as those outlined in Freddie Mac’s value-add loan documentation, rather than rely on a generic income target.
How does DCF modeling differ from a simple cap rate for value-add deals?
A cap rate approach assumes stable income and misses the transition period that defines a value-add deal. Discounted cash flow modeling accounts for renovation timing, lease-up pace, and staged rent growth, which is why RICS guidance treats DCF as the more reliable method for assets expected to change materially over the hold period.